Showing posts with label Securities and Exchange Board of India. Show all posts

Wednesday, July 1, 2020

United Spirits case: Sebi slaps Rs 3 cr penalty for insider trading


Markets regulator Sebi on Tuesday imposed a penalty totalling more than Rs 3 crore on three persons for insider trading activities in the shares of United Spirits Ltd.


Markets regulator Sebi on Tuesday imposed a penalty totalling more than Rs 3 crore on three persons for insider trading activities in the shares of United Spirits Ltd.
The watchdog has slapped a fine of Rs 1.32 crore on Poonam Haresh Jashnani, Rs 93.24 lakh on Haresh Parmanand Jashnani and Rs 80.76 lakh on Varun Haresh Jashnani.

An investigation was carried out with respect to the scrip of United Spirits Ltd (USL) for the period from January to April, 2014 as well as into the possible violation of norms by these three persons.

Sebi found that Jananis indulged in insider trading activity in USL shares on the basis of information passed by Nishant Gupte, who was the global business development manager (mergers and acquisitions) at Diageo.

He was in possession of Unpublished Price Sensitive Information (UPSI) relating to the open offer for acquisition of shares of United Spirits by Relay BV, together with Diageo Plc as the person acting in concert.

Gupte, who is the son-in-law of Haresh and Poonam and husband of Varun's sister, was part of the core team which represented Diageo/PAC in the transaction to consolidate shareholding of the acquirer in USL and was guiding the team since the beginning of the transaction lifecycle.

In three separate orders, Sebi said trades of Haresh, Varun and Poonam showed a strong preponderance of probability that they were executed when they were in possession of UPSI.


Wednesday, May 27, 2020

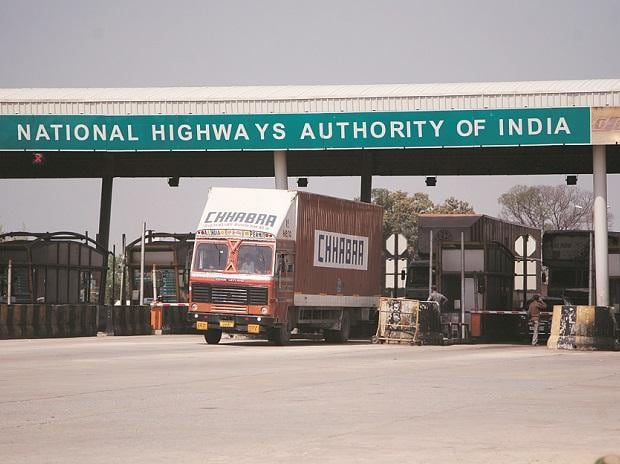
Sebi imposes a penalty of Rs 7,00,000 on NHAI for disclosure lapses


During its investigation, Sebi found that NHAI delayed filing of its half-yearly financial results by 4 days to 78 days between 2015-16 to 2018-19.


Capital markets regulator Sebi on Tuesday imposed a penalty of Rs 7 lakh on the National Highways Authority of India (NHAI) for delay in making timely disclosure about financial results.

Sebi had conducted an examination in the matter of NHAI from financial year 2015-16 to 2018-19.

During its investigation, Sebi found that NHAI delayed filing of its half-yearly financial results by 4 days to 78 days between 2015-16 to 2018-19.

The regulator had advised NHAI for strict compliance with the LODR (Listing Obligations and Disclosure Requirement) Regulations in future.

However, despite the advisory by Sebi, NHAI did not submit the financial results on time with respect to the half year ending on September 30, 2018 and March 31, 2019.
The results were submitted with a delay of 19 days and 78 days, respectively.

"There was repeated failure (seven instances during FY 2015-16 to FY 2018-19) on the part of the noticee (NHAI) regarding compliance with the provisions ...LODR Regulations," Sebi said in an order.

Accordingly, the regulator imposed a penalty of Rs 7 lakh on NHAI.
In its reply to a show cause notice (SCN) issued by Sebi, NHAI said it seeks approval of the majority of its board members in relation to all matters including approval of unaudited half yearly results.


Monday, April 13, 2020

Mauritius funds eligible for Category-I status, move could boost investment


Nearly 80 per cent of FPIs coming from Mauritius are currently classified as Category-II.

The government has specified foreign portfolio investors (FPIs) from Mauritius as eligible for taking up Category-I licence — a move that could boost investment from the region.

Nearly 80 per cent of FPIs coming from Mauritius are currently classified as Category-II.

According to experts, all these investors may be shifted to Category I on payment of the requisite fees for the license. Despite its treaty amendment with India, Mauritius remains the second-largest source of FPI money and the move could boost investment from there.

“The taxation overhang on funds investing through Mauritius is gone because no indirect transfer is applicable to Category 1. These funds will also be able to issue and subscribe to participatory notes,” said Khushboo Chopra, head of business development-India, Sanne, a global provider of alternative assets.

This year’s Budget had clarified that Category-II FPIs would be subject to indirect transfer provisions, which were earlier applicable to unregulated funds falling under Category-III.

Being part of Category-I implies lower compliance burden, simplified know-your-customer norms and documentation requirements, and fewer investment restrictions.
“This is a major development for the Mauritius International Financial Centre (IFC). It brings the element of certainty back to Mauritius jurisdiction with respect to FPI investments. As a premier IFC, we continue to play an important role in driving quality investments into the region and emerging markets, while ensuring adherence to the best practices.

This development reaffirms the position of Mauritius as a major IFC for foreign portfolio investment, as well as the confidence of investors in our jurisdiction,” said Harvesh Seegolam, governor of the Bank of Mauritius and former chief executive of FSC Mauritius.


Wednesday, April 8, 2020

Sebi relaxes guidelines for investment through non-FATF countries

Move to benefit investors from countries and regions like Mauritius, Cayman Islands who are eyeing Category-I licence.


The Securities and Exchange Board of India (Sebi) has relaxed its guidelines for foreign portfolio investors (FPIs) seeking a Category-I licence, a move seen giving a boost to overseas investment in stocks.

Investors from countries which are not Financial Action Task Force (FATF) members can still qualify for such registrations if the countries are specified by the Indian government. The move may benefit funds and investments routed through countries, such as Mauritius and those from West Asia, and aid overseas flows coming into India, said experts.

At present, the FATF has 39 members, including Australia, Singapore, Luxembourg, South Korea, the US, the UK, and China. West Asian nations, such as Bahrain, Oman, Qatar, Kuwait, and the UAE are not its members.

Nearly 80 per cent of FPIs were put under Category-I after the reclassification of three categories into two in September last year. Being part of Category I implies lower compliance burden, simplified know-your-customer (KYC) norms and documentation requirements, and fewer investment restrictions. Such investors can subscribe and issue offshore derivative instruments and are not subject to indirect transfer provisions.

Prior to the reclassification, less than 3 per cent FPIs were part of Category-I and more than four-fifths were part of Category-II. About 13 per cent of the funds were classified as Category-III.

“The move will expand the list of countries eligible for the Category-I status beyond the FATF member countries. It will not only mean fewer KYC requirements for FPIs from such countries but also exemption from indirect share transfer regulations,” said Rajesh Gandhi, partner, Deloitte India. “Along with the MSCI index rejig, this will help boost inflows into India, especially from India-focused funds.”

Experts reckon non-FATF countries, such as Mauritius and those from West Asia, may now lobby to get included in the list of specified countries to be put out by the Indian government

Monday, April 6, 2020

Rush hour and tougher questions ahead for both Mint Raod and banks


Piecemeal regulatory forbearance will not go far and tougher questions will be asked of both Mint Road and banks, reports Raghu Mohan.


“We must always remember that tough times never last; only tough people and tough institutions do,” said Reserve Bank of India (RBI) Governor Shaktikanta Das, when he announced a raft of measures to tackle the fallout of coronavirus (Covid-19) on the economy. It was a signal the days ahead will stretch both banks and Mint Road; so be prepared. Are we?

The asset quality of banks and the demands on their capital position due to its further deterioration must rank among the top concerns. The central bank has moved on the double to put in place a three-month moratorium on the servicing of term loans. But there has been no relook at income recognition and asset classification norms, the status of additional provisioning under the central bank’s June 7 circular, and the road ahead under the Insolvency and Bankruptcy Code (IBC) in these stressful times.

Says Divyanshu Pandey, Partner at J Sagar Associates, “There is good reason to give a three-month break for the timelines under the June 7 circular. An idea has been floated that the IBC process itself may be suspended for six months. A like thought process may be good for the June 7 circular as well.”

The merger of four sets of state-run banks, effective April 1, has led to a reset of a quarter of the banking system’s assets, and there is nothing to suggest that these entities will not require fresh capital down the line – and we have a handle on only their pre-Covid asset quality as on date. This holds true for private banks as well and may call for a rethink of their current capital structures.


Sunday, April 5, 2020

New defence procurement policy gets mixed reaction from industry


The MoD has invited suggestions and recommendations by April 17. After that, DPP-2020 will be promulgated and will govern all acquisitions initiated thereafter.


The defence industry has expressed mixed reactions to the proposed Defence Procurement Procedure of 2020 (DPP-2020), which the Ministry of Defence (MoD) released in draft form on February 20.

The MoD has invited suggestions and recommendations by April 17. After that, DPP-2020 will be promulgated and will govern all acquisitions initiated thereafter. It will supersede DPP-2016 as the MoD’s handbook for purchasing of weapons, warships and equipment from the defence capital budget.

A Business Standard survey of small, medium and large defence firms reveals broad agreement that DPP-2020 has been hurriedly finalised and uploaded. Important annexures and appendices have been left out and even page numbering has not been done.

Like successive DPPs since the first in 2002, the draft DPP-2020 is longer and more complex than any other that preceded it. This despite the MoD’s stated aim of simplifying acquisition procedures to speed up the military’s modernisation. A 719-page long, the draft DPP-2020 is far wordier than its predecessor — the 430-page DPP-2016, which has, over the past four years, been amended 47 times for business process reengineering.

This is so, even though the draft DPP-2020 excludes an entire chapter on the Strategic Partnership Model of procurement since no changes are being recommended to the version in DPP-2016.

Abhishek Jain of software firm Zeus Numerix sees a change of soul in DPP-2020. Unlike previous DPPs, which he says primarily laid out guidelines on procuring foreign equipment, this time around there is a full chapter on indigenous innovation, including how single vendor purchase is acceptable for an innovative product developed by an Indian company, which has 50 per cent indigenous content.